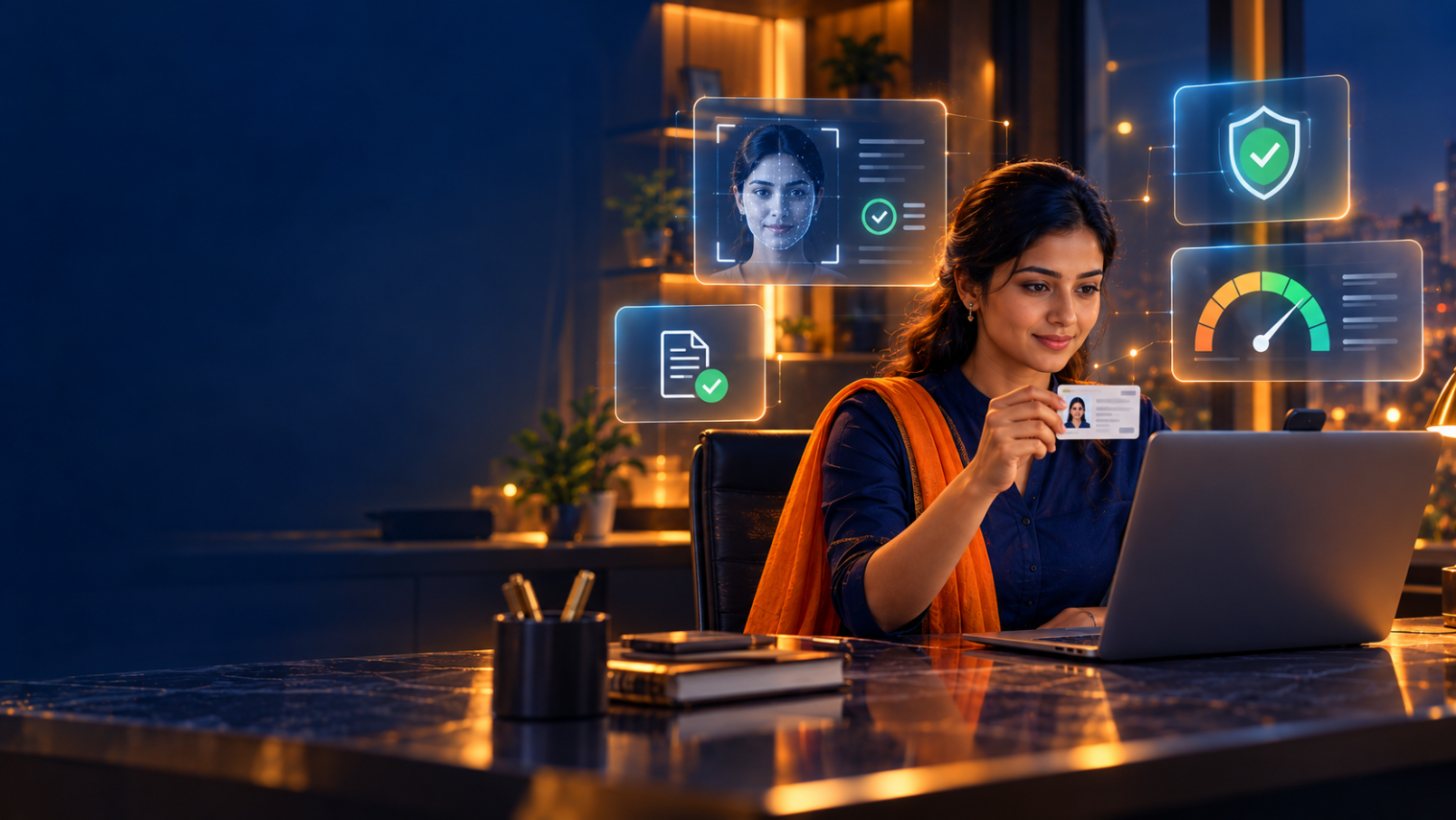
KYC verification software is a system that confirms a customer's identity and documents in real time — verifying PAN, Aadhaar, bank account, GST, voter ID and more through secure APIs. Instead of collecting photocopies and checking them by hand, a lender, co-operative or fintech verifies each customer in seconds, cuts fraud, and keeps an audit trail that stands up to regulators and the DPDP Act.
What KYC verification software checks
- PAN verification — name and status against the income-tax database.
- Aadhaar verification — offline Aadhaar/XML and OTP-based checks, UIDAI-compliant and without storing the full number.
- Bank account (penny-drop) — confirms the account exists and matches the name before disbursing or refunding.
- CKYC — pulls the Central KYC record so returning customers aren't re-verified.
- GST, voter ID, driving licence, passport — business and individual identity checks as needed.
- Face match and liveness — match a selfie to the ID photo for remote onboarding.
Why KYC matters for co-operatives and lenders
Every loan, deposit account or disbursement carries identity risk. Manual KYC is slow, error-prone and hard to audit — and a single mismatched bank account can send money to the wrong person. API-based KYC verifies at the moment of onboarding, so bad records never enter the system. For lenders it also speeds up loan origination: a borrower's PAN, bank and identity are confirmed before the file moves forward. For the technical side, see KYC verification APIs, explained.
KYC, data security and the DPDP Act
India's Digital Personal Data Protection (DPDP) Act, 2023 makes identity data a serious responsibility: it must be collected with consent, used only for the stated purpose, secured, and not retained longer than needed. Good KYC software is built around this — consent capture, encryption, minimal storage (for example verifying Aadhaar without storing the full number), and complete audit logs. For how this affects temples and co-operatives, see What the DPDP Act means for temples and co-operatives.
How to choose a KYC verification provider in India
- Coverage: PAN, Aadhaar, bank penny-drop, CKYC, GST and more in one integration.
- Speed and uptime: real-time responses and a reliable SLA.
- Developer experience: clean REST APIs, a sandbox, and bulk verification.
- Compliance by design: DPDP-aligned consent, encryption and data minimisation.
- Audit logs: every check recorded for regulators and internal audit.
- Security certification: VilaSoft is ISO 27001:2022 certified.
Why fintechs and lenders choose VilaSoft CrediSure
CrediSure provides PAN, Aadhaar, bank penny-drop, CKYC, GST and more through clean REST APIs with a sandbox and bulk verification — built for DPDP-aligned consent, data minimisation and full audit logs, on an ISO 27001:2022-certified platform. It plugs straight into lending, co-operative and fintech onboarding flows.
Frequently asked questions
What is KYC verification software?
It is software that verifies a customer's identity and documents — PAN, Aadhaar, bank account, GST and more — in real time through secure APIs, with an audit trail.
What is a penny-drop bank verification?
A penny-drop deposits a tiny amount to confirm a bank account exists and the name matches, before you disburse money or process a refund.
Is Aadhaar verification DPDP-compliant?
CrediSure uses UIDAI-compliant offline and OTP methods and data minimisation — verifying without storing the full Aadhaar number — in line with the DPDP Act.
Can it verify customers in bulk?
Yes. CrediSure supports bulk verification and clean REST APIs with a sandbox for integration.
Who uses KYC verification software?
Lenders, NBFCs, credit co-operatives, fintechs and any business that must confirm customer identity before onboarding or disbursement.
What does it cost?
Usually priced per verification or by volume; VilaSoft shares a quote after a free demo — request one here.